A Conversation with Chris Bitter, Senior Wine & Grape Analyst
The latest edition of Winescape examines import competition. American AgCredit’s wine industry analyst on their Terrain team, Chris Bitter, discusses what the data reveals, where the biggest challenges exist, and what opportunities may lie ahead for producers.
Q: Everyone seems to be talking about exports. Share what made you look at the other side of the equation, imports.
Chris Bitter: News headlines have been filled with “tariff” and “retaliatory tariff” for more than 18 months, but imports have been gaining market share for decades. Imports now account for about 35% of the wine consumed in the United States, which is near a historic high. When overall demand is growing, market share shifts don't always draw much attention. When demand is shrinking, every point of market share matters.
Q: Much of the discussion focuses on imported bulk wine. Is that the whole story?
Chris Bitter: No. Bulk wine imports are certainly part of the conversation, but they're not the whole picture. One of the biggest misconceptions is that import competition is only happening at the lower end of the market. The data shows that packaged imported wines have also gained significant share and are responsible for much of the increase in import penetration over recent years. The competitive landscape is broader than many people realize.
Q: Are certain wine categories more exposed than others?
Chris Bitter: Absolutely. Imports perform particularly well in sparkling wine, Sauvignon Blanc and Pinot Grigio. These categories account for a substantial portion of imported wine sales and align closely with some of the fastest-growing consumer preferences we've seen over the past decade. Meanwhile, domestic producers tend to hold stronger positions in categories like Cabernet Sauvignon and other red wines. Understanding where imports are winning can help inform strategic decisions.
Q: If imports continue gaining share, what does that mean for growers and wineries?
Chris Bitter: It creates challenges, but it also highlights opportunity. One of the exercises I explored in the report was what would happen if domestic producers regained even a modest amount of market share. The potential impact on domestic wine sales and grape demand is significant. That's why this discussion matters. It's not simply about what's being lost. It's also about what could potentially be regained.
Q: Can domestic producers realistically compete on price?
Chris Bitter: In entry-level wines, no. Production costs in California have increased substantially, while imported bulk wine from countries such as Chile and Australia continues to have a meaningful cost advantage. I don't believe the future success of the U.S. wine industry will come from trying to become the lowest-cost producer. That's not where our competitive advantage lies.
Q: So where do you see the biggest opportunity?
Chris Bitter: I believe the greatest opportunity is in the popular-premium and premium segments. U.S. producers are often better positioned to compete on quality, innovation, vineyard sourcing and brand strength than on cost alone. The challenge is less about winning a race to the bottom and more about creating compelling wines and brands that justify their value to consumers.
Q: What should wine industry leaders be watching as they plan for 2027?
Chris Bitter: Beyond imports, they should watch the broader economic environment and how it affects discretionary spending. The wine market showed modest improvement during the first half of 2026, but challenges remain. At the same time, the smaller California crop may help reduce inventory overhang and move grape supply and demand toward better balance over time. These interconnected trends will shape the market outlook heading into next year.
Q: What's the one takeaway you hope readers gain from your latest research?
Chris Bitter: The import discussion is important, and it's nuanced. There are real challenges, but there are also meaningful opportunities. Understanding where imports are winning, why they're winning, and where domestic producers can compete most effectively is critical for the industry's future.
Read the Full Analysis
These insights are explored in greater detail in the latest edition of Winescape – Fall 2026, including market trends, the harvest outlook, import market-share analysis, and strategic considerations for wineries and growers navigating today's evolving market.

Situation: Imports now account for about 35% of all wine consumed in the U.S., near an all-time high and up meaningfully from 2020. The rise has gained more attention as overall U.S. wine sales have slowed.
Finding: Import substitution represents an enticing opportunity to stimulate domestic wine and grape sales in today’s challenging environment. But efforts to improve competitiveness must be thoughtful and not create unintended consequences for wineries that rely on imports.
Outlook: Regaining market share will be difficult in the entry-level segment, where imports have a clear cost advantage. The better opportunity likely lies in the popular-premium and premium segments, where U.S. producers can compete more effectively on quality.
This issue:
Examines the slight progress in wine sales in the first half of 2026
Shares an update on the grape crop and the pros of a small harvest
Spotlights import competition and how the U.S. could regain market share
Chris Bitter, Senior Wine and Grape Analyst at Terrain, discusses California vineyard valuations and the current state of the agricultural real estate market based on the latest Winescape newsletter, "Tangled Vines."
Prime appellations maintain stronger prices due to reputation and secured grape contracts, while marginal vineyards face steep devaluations. With limited transactions and a disconnect between seller expectations and buyer willingness to pay, Chris explains why valuing vineyards is difficult right now. He anticipates further downward pressure over the next 12-18 months before stabilization, but offers growers practical strategies to facilitate sales.
This conversation is essential viewing for vineyard owners and industry professionals navigating California's agricultural real estate market.
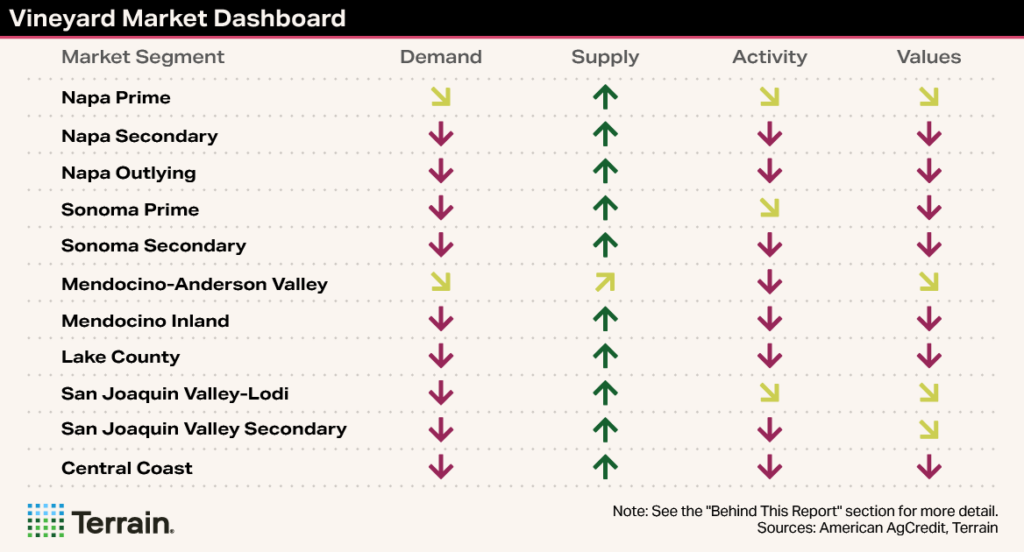
Situation: A severe decline in grape demand and prices, along with rising grape production costs, have pulled down California’s vineyard values.
Finding: The market is distinctly bifurcated, with an uneven decline across and within market segments. Considerable buyer interest remains for top-tier vineyards in premier appellations, whose value has held up relatively well. Vineyards with strategic appeal to a winery or those that can offer guaranteed income streams are also faring well in the market.
Outlook: A softening in vineyard values in the near term is fairly certain. But under my base-case scenario that the grape market will begin to stabilize in 2027 or 2028 in most regions, the vineyard market bottom shouldn’t be far behind. The longer-term trajectory of vineyard values will depend largely on the strength of grape price appreciation, which will vary across market segments.
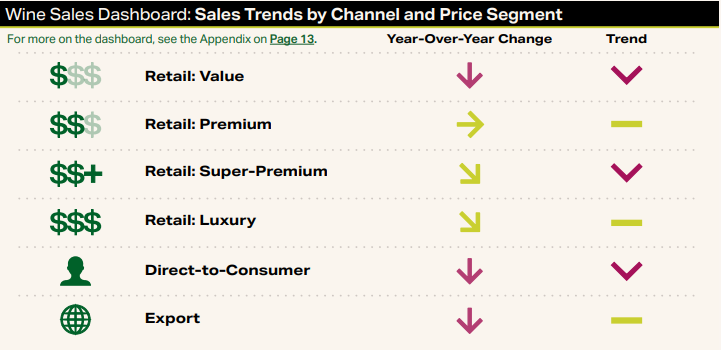
A tumultuous 2025 economy likely depressed wine sales. In 2026, the higher-end segments should continue to outperform, and the grape market should be less oversupplied when harvest begins.
REPORT SNAPSHOT
Situation: Wine sales softened across the board in 2025, and prices stagnated as a result of consumer price sensitivity and heightened competition among producers trying to move excess inventory. Although the wine market slump continues, relative bright spots include premium and luxury wines, nonalcoholic and ready-to-drink wines, and white and sparkling wines.
Outlook: I’m not expecting a material change in the trajectory of U.S. wine sales in the near term, though I see the most potential for progress in the second half of the year. There should be less excess supply burdening the grape market when the 2026 harvest begins than there was in 2025.
Impact: For wineries that are fairly certain about their grape needs, it may be prudent to act sooner rather than later.
Download the Spring 2026 issue of Winescape
This issue:
- Shines a light on the influence of the economy and consumer preferences
- Gives an update on the 2026 outlook for the wine and grape markets
- Draws implications from the 2025 crush for the 2026 grape market
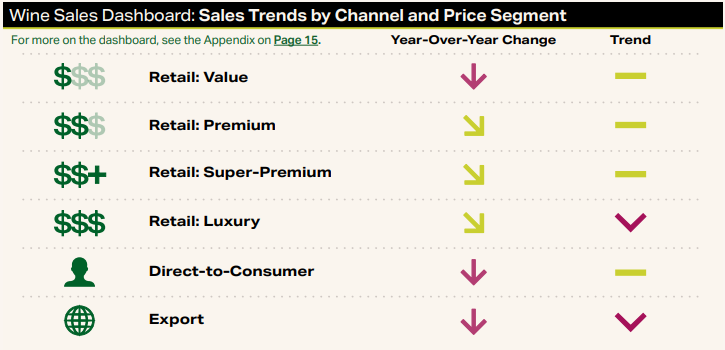
An exceptionally small 2025 grape harvest would help balance wine inventories and potentially stimulate grape demand next year
There wasn’t much change in the complexion of the wine market in the third quarter. Sales continued to decline across channels and price points, though at varying rates. Some segments improved while others worsened. Wine exports continued to flag because of provincial bans in Canada.
I continue to believe the slump is mainly structural, particularly at the lower end of the market (see Page 3). But I also believe economic factors such as inflation and depressed consumer sentiment have played a role, and I expect wine sales to firm up once the economic backdrop improves. Unfortunately, we aren’t expecting much change in the economy, for better or worse, in the months ahead, so the wine market isn’t likely to see much improvement either.
2025 was a painful year for California grape growers. Weather was an issue, but the grape market proved to be an even greater challenge. There simply wasn’t enough demand to absorb all the fruit due to slumping wine sales, excess inventory and gun-shy buyers. Hundreds of thousands of tons were thought to have been left hanging. Experts believe the crush will come in below 2.5 million tons, which would be the slightest of the 21st century.
I expect some improvement in the grape market in 2026 because of the ongoing supply-side correction (nearly 40,000 acres were removed between October 1, 2024, and August 1, 2025) and a potential reduction in wine inventory stemming from the small harvest, though this is far from certain.
This issue’s Trending Topic focuses on the wine inventory glut (see Page 9). The inventory overhang is difficult to measure now, let alone forecast, because of imperfect data and uncertainty regarding the 2025 crush size and trajectory of wine sales. If the harvest turns out to be as small as predicted, inventories should be more balanced heading into next year’s harvest. However, my analysis indicates that a wide range of outcomes are possible.
A material reduction in inventory would stimulate grape demand next year. Under my base-case scenario, I expect more grapes to be sold in 2026. This, coupled with lower grape production potential, should result in a better balance between supply and demand in the aggregate. No matter the scenario, the balance will continue to vary widely across appellations, varieties and quality tiers.
Wineries and growers should closely monitor the situation in the months ahead as fresh datapoints are released. I’ll provide an update in the spring edition of “Winescape.”
This issue:
- Assesses the nation’s wine inventory glut and how quickly it might be resolved
- Gives an update on the size of the California grape harvest and its potential impact on inventory
- Shares an early outlook for how the wine and grape markets will fare in 2026
Download the winter issue of Winescape
It’s no secret that people are drinking less.
The consistent, downward trends in alcohol consumption are presenting significant challenges to the wine industry, which is already having to operate in a complex, competitive marketplace.
In order to dissect what is happening in the world of wine and figure out how to make adjustments, industry leaders need solid information on which to base their current business practices and future projections.
Fortunately, the industry has Terrain, a group of experts providing exclusive insights and forecasting to customers of American AgCredit and other participating Farm Credit associations in order to promote a more vigorous agricultural economy.
Chris Bitter, Ph.D., a senior wine and grape analyst with Terrain and American AgCredit, has recently written two comprehensive articles for "Winescape", a publication that delves into current wine sales data and explores what those show about trending topics such as overall alcohol consumption.
We spoke to Bitter about his work that, importantly, identifies significant opportunities for wine to reclaim market share.
Trends
Retail wine sales fell across all price segments in the first half of 2025. Direct-to-consumer sales, while still down, firmed up a bit over the summer, but exports deteriorated markedly in the second quarter as shipments to Canada collapsed. Sluggish economic growth, sticky inflation and a softening labor market are the most likely scenarios in the near term, which will not help the wine industry. Unfortunately, I’m not expecting much improvement in the near term.
The five primary structural factors are demographics, cannabis, GLP-1 class drugs, less in-person socializing, and changing attitudes toward alcohol and health.
Demographics
The U.S. population is both aging and becoming more diverse. This is a problem for alcohol because consumption typically declines later in life and multicultural consumers drink substantially less than their non-Hispanic white counterparts. The move towards moderation or abstinence is highest among younger generations, particularly Gen Z and, to a lesser extent, millennials. We’ve noted that the current decline in alcohol use has been more pronounced for men than women and for non-Hispanic whites.
Cannabis
Cannabis is now fully legal in 24 states and the District of Columbia, and marijuana use has surged since 2012, when Colorado and Washington first legalized cannabis as a recreational substance. In addition, THC-infused drinks have skyrocketed in popularity, with low-dose hemp-based versions even being sold in some states where cannabis is illegal due to a loophole in the 2018 farm bill. Research is still inconclusive; however, cannabis likely has been stealing some recreational and social occasions from alcohol.
GLP-1 class drugs
Drugs such as Ozempic, Mounjaro and Wegovy, which help regulate blood sugar and appetite, also reduce desire for alcohol. Studies show that people taking the medications have reduced their drinking, with one finding a reduction of 70%. Although a relatively small percentage of the population is on the drugs now, 35% of adults expressed interest in a recent PwC survey, and drugmakers are beginning to reduce prices, making adoption almost certain to surge in the years ahead.
Less in-person socializing
Americans are spending progressively less time socializing in person, in both their personal and professional lives. A recent study shows that leisure time spent socializing fell by 20% from 2014 to 2022, while time spent on social media and in front of screens rose sharply. Given that alcohol has long been associated with social gatherings, it makes sense that less in-person socializing is reducing the number of potential drinking occasions.
Changing attitudes toward alcohol and health
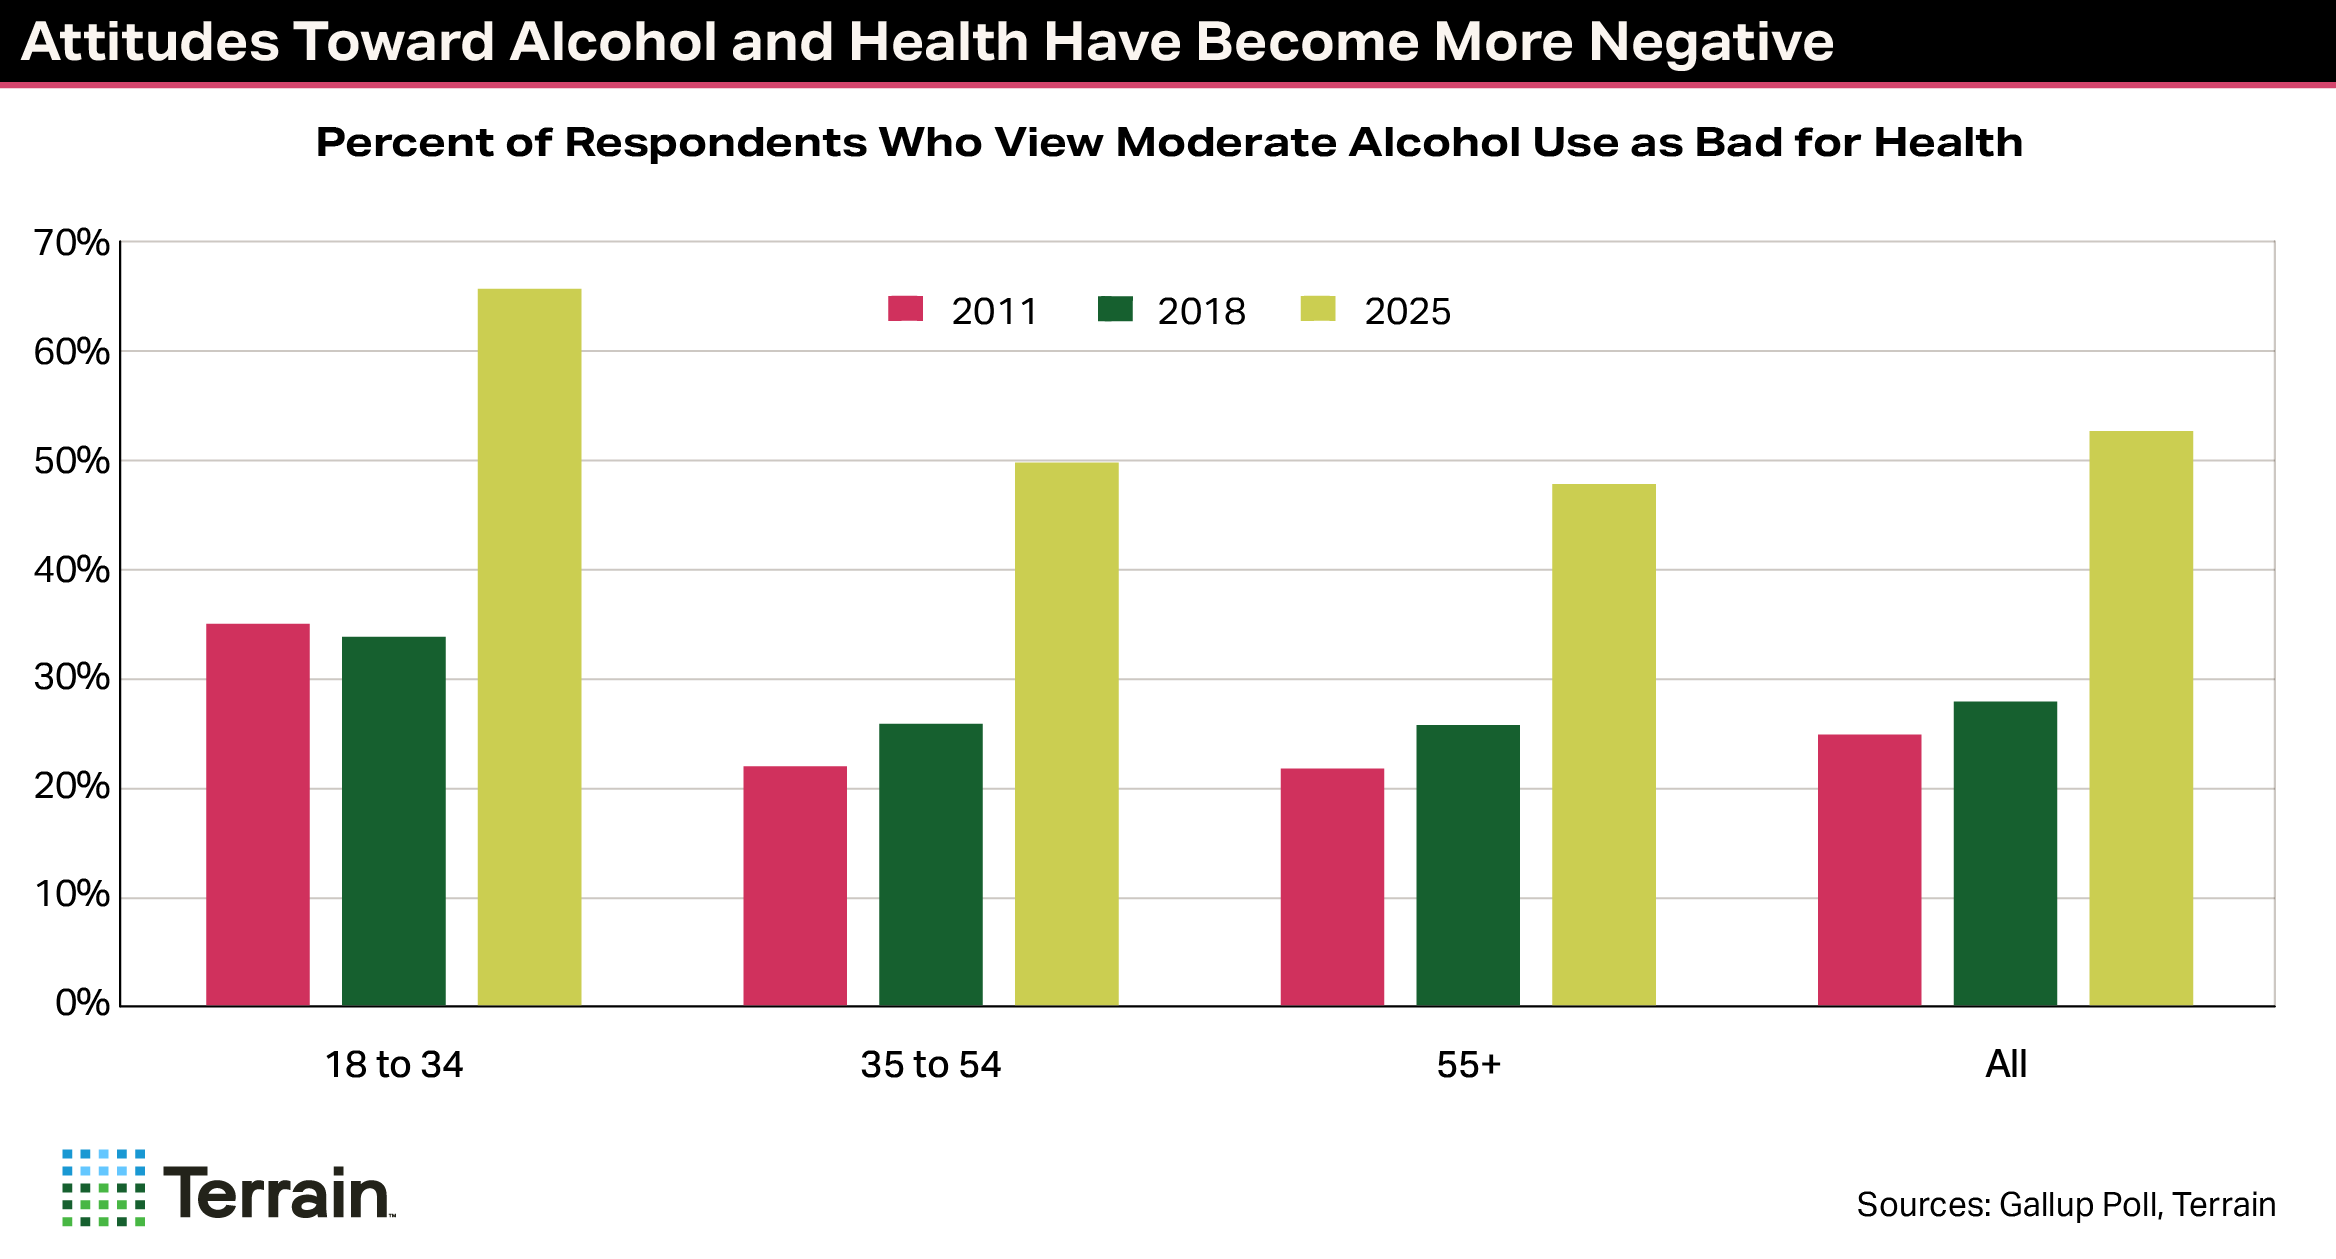
A Gallup poll conducted in 2018 found that 28% of respondents said that moderate drinking is bad for your health. In 2025, that number rose to 53%. Rising health skepticism has almost certainly weighed on alcohol consumption in recent years. A sophisticated and well-funded anti-alcohol movement that has gained influence over the last decade has accelerated the swing. That movement will continue to exert its influence on public opinion and policy going forward.
Some opportunities involve premiumization, wine styles and packaging formats.
Premiumization
If consumers drink less, they are apt to treat it like an indulgence and consume higher- quality beverages when they do drink. Presumably, they will also be able to spend more, as they are purchasing fewer bottles, so the premium and luxury segments of the industry should be less impacted. It will be essential to maintain quality.
Wine styles
If consumers are more concerned with health and wellness or taking GLP-1 drugs, lighter, crisper wines with less oak, alcohol and calories may be more appealing. This has implications for both winemaking and grape-growing practices.
Packaging formats
If consumers are drinking alone or less due to age, health concerns or GLP-1 drugs, the 750ml bottle may not be suitable on as many occasions. There may be a shift toward smaller formats (splits, cans, etc.) and containers that preserve freshness for longer periods of time (such as bag-in-a-box wine).
I believe wine is well-positioned to attract consumers, especially those concerned with health and wellness, as it has some distinct advantages over other alcoholic beverages.
It is a natural product with no fat, generally no added sugar, and dry wines are relatively low in carbs and calories. Moreover, the antioxidants in wine, particularly red, are thought to promote heart health when consumed in moderation.
Wine is also steeped in history, culture and geography. It is a beverage meant to be savored and shared with family and friends. In essence, it is the drink of moderation.
These virtues should appeal to consumers of all ages. The industry must strive to tell the story of wine in a simpler and more compelling manner.
For more information, on Chris Bitter, Terrain and American AgCredit, go to: https://www.terrainag.com
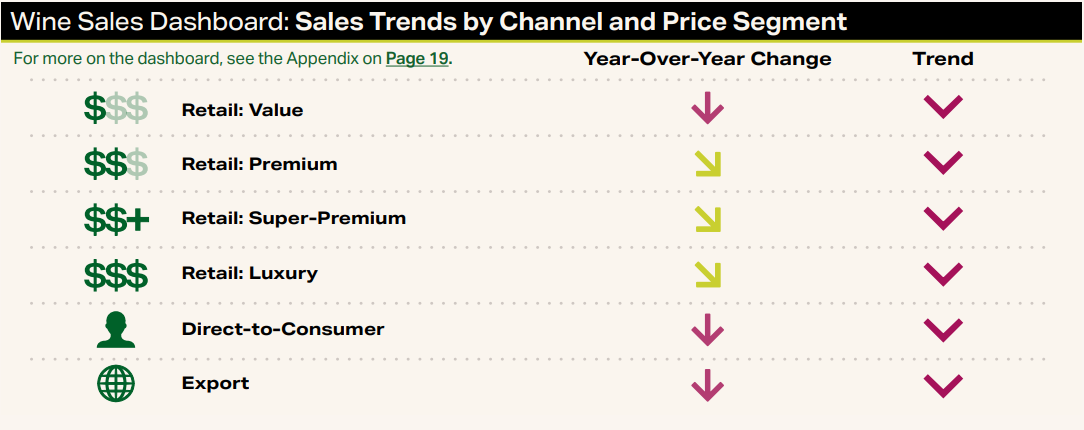
Price-sensitive consumers have kept a lid on wine sales this year, while grape sales are likely to remain slow. As for the moderation movement, a range of factors are contributing.
It was a disappointing first half of the year for U.S. wine sales as a shaky economic backdrop quashed the signs of progress that were evident in late 2024. Nonetheless, there has been modest improvement in some areas since spring.
Retail wine sales fell across price segments in the first half but declined at a slower pace in the second quarter than in the first (see Page 3). Following a bleak first five months of 2025, direct-to-consumer sales, while still down, firmed in June and July. Alternatively, exports deteriorated markedly in the second quarter as shipments to Canada collapsed.
Unfortunately, I am not expecting much improvement in the near term.
The economic outlook remains murky, but the Terrain team believes that slow economic growth, a gradually eroding labor market, and sticky inflation are the most likely scenario. Consumers are apt to remain gloomy and price-sensitive.
The California grape crop looks healthy, though perhaps a bit light at this point. Grape sales remain painfully slow, and I don’t expect a resurgence before the harvest concludes. Fruit will almost certainly be left hanging again this year.
This issue’s Trending Topic focuses on the causes of the recent decline in alcohol consumption (see Page 8). Transitory influences, including a post-pandemic hangover and economic pressures, are playing a role, but structural factors appear to be the root cause.
These include demographics, competition with cannabis, GLP-1 drugs, health concerns, and less socializing in person. None of these headwinds are likely to dissipate soon, so I expect consumption to decline for the foreseeable future.
It is impossible to predict the magnitude of the drop, but it could be more pronounced than during the last drinking recession (1980 to 1995) simply because the adult population is growing at a much slower rate.
The moderation movement is an obvious challenge for the wine industry. Wine will need to take market share just to hold sales volumes steady. I believe it has some advantages over other alcoholic beverages in the battle for drinkers, but it must tell a more compelling story.
The premium and luxury segments look better positioned with respect to the moderation trend, and I expect the shift in consumer preferences toward lighter, lower-alcohol wines to continue. This has implications for both wine making and grape growing practices. Finally, consumers are apt to gravitate toward smaller formats or packages that preserve freshness for longer.
This issue:
• Identifies the root causes of declining alcohol consumption
• Shares a lackluster market update for the first half of 2025
• Presents opportunities related to shifting consumer preferences
Download the Fall 2025 Winescape
Event Type: Webinar
Location: Vritual
Date: 9/17/2025
This free webinar is designed for young, beginning, or small-scale farmers looking to build a stronger financial foundation in agriculture and will include:
- The fundamentals of building a business plan, crafting an annual budget, and understanding your balance sheet
- Practical insights from an experienced lender
- Access to free resources that offer additional tools to support your financial journey
As the agricultural landscape evolves, so do the financial tools and strategies needed to support the next generation of producers.
Wednesday, September 17 at 12 p.m. PT